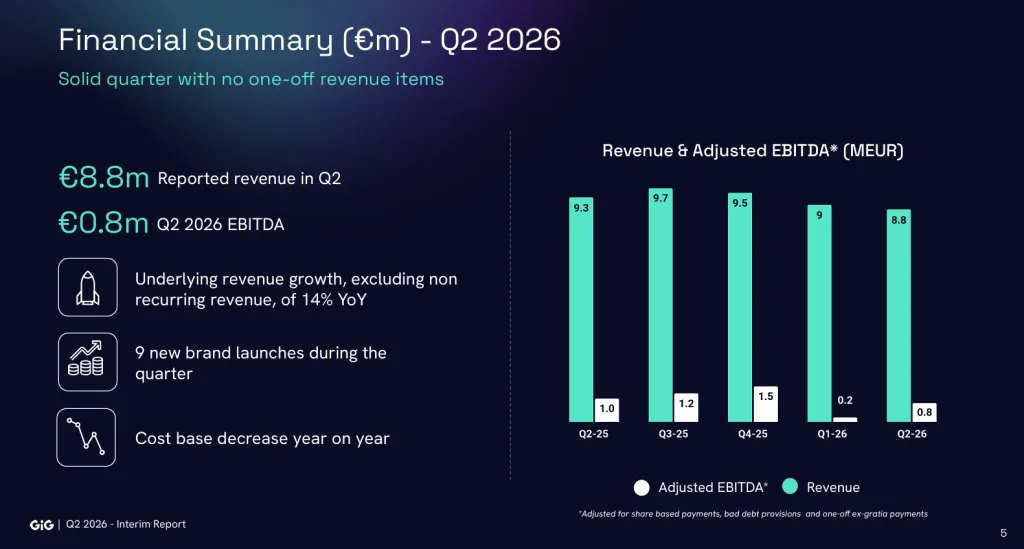
GiG Software Plc reported Q2 2026 results, and the headline is fairly modest. Revenue for the quarter ended 30 June came in at €8.8m, down 5% year on year. Adjusted EBITDA was €0.8m, but the key driver of the quarter wasn’t revenue, it was a large bad-debt provision of close to €3m, linked to a customer insolvency, which pulled the operating loss materially lower.
Q2 revenue of €8.8m compares with €9.3m in the prior year. GiG attributes the decline mainly to the insolvency of Richmond Atlantic, alongside lower setup fees. Adjusted EBITDA slipped to €0.8m from €1.0m, taking the margin down to 9% from 11%.
The real pressure shows up in the operating line. The company recorded an operating loss of €6.9m, compared with a €3.7m loss in Q2 2025. The largest contributor was an exceptional bad-debt provision of €2.9m tied to the Richmond Atlantic insolvency. On cash, GiG reported €3.5m in cash and equivalents on 30 June, down from €4.3m a year earlier.
The half-year trend looks similar. H1 revenue was €17.8m, down 3%, while adjusted EBITDA was €1.0m. GiG says it delivered €4.5m in annualized savings in full. It also started a further €6.0m of annualized savings in June through the closure of loss-making partners and markets. The company additionally flagged a planned closure of its Alira Spain platform in 2027.
Despite the financial drag, there was some commercial momentum: four contract renewals in the quarter, three new operators signed for Alberta, and a day-one launch in Alberta with partner LuckyDays. GiG also reported nine brand launches across the UK and Canada.
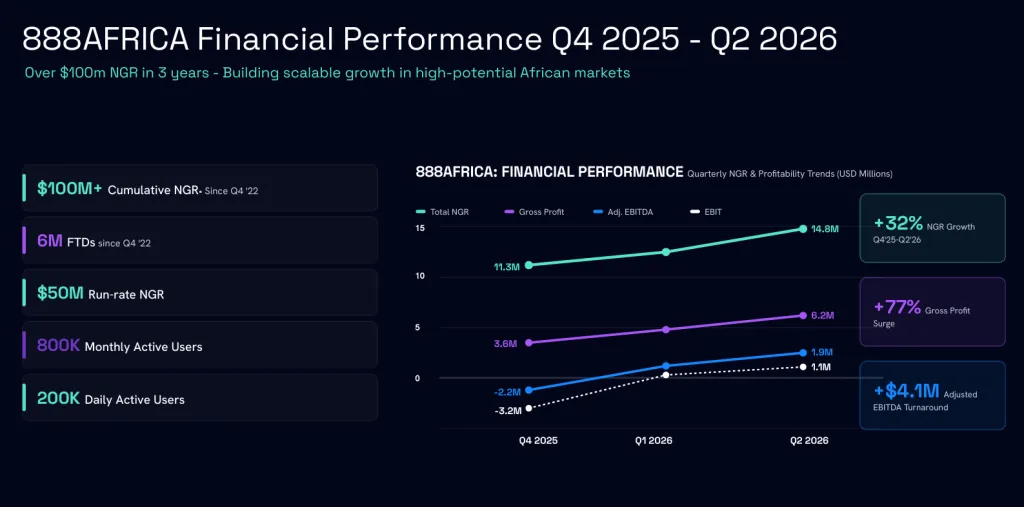
Behind the numbers sits a major strategic shift. After the period ended, GiG confirmed it is in the final stages of buying an 80% stake in 888AFRICA from Evoke, with the existing management team retaining 20%. GiG describes 888AFRICA as a cash-generative, profitable, fast-growing African B2C operator with a market-leading position in Mozambique, plus operations in Angola and Tanzania.
It runs at around $50m in annualized NGR. The consideration is $19.2m. CEO Richard Carter framed the move around long-term growth prospects in the region, driven by factors such as demographics, mobile adoption, and regulatory tailwinds.
Taken plainly, this is a shift from being primarily a B2B iGaming technology supplier toward taking control of a B2C operator effectively creating a second “engine” with a different risk profile. GiG says the deal will be funded through a mix of equity and convertible debt with existing shareholders.
There are two issues worth watching closely. First, the transaction isn’t closed. GiG describes it as an initial indicative agreement, subject to final approvals and signing of the share purchase agreement. Carter expects completion by the end of September, but that’s still an estimate rather than a confirmed close.
Second, the bad debt hit creates a legitimate question about customer concentration and credit risk. If a single insolvency can trigger a ~€3m provision in one quarter, investors may want clarity on how diversified the customer base is, especially as GiG’s top line is already under pressure.
Going forward, the focus is on delivery: signing the SPA, closing the acquisition, and integrating 888AFRICA successfully. Pending completion, GiG guided to combined FY 2026 revenue of €44–48m and adjusted EBITDA of €5–7m, assuming a full contribution from 888AFRICA in Q4.
For partners and operators, the practical implication is that GiG is trying to trim and refocus its core while placing its growth bet in African B2C. Whether this makes GiG structurally stronger will depend on whether it can stabilize and rebuild its core while integrating the new business on time. For now, the direction is clear. The next step is proving it through the numbers.