Botswana has a phone in almost every hand, but millions of adults still lack access to the formal banking system. Mobile penetration is about 166%, equivalent to roughly 4.2 million connections for a population of 2.5 million.
Yet an estimated 38% of adults remain unbanked. Turning that connectivity into a financial tool is where Mukuru comes in. Mukuru is a digital financial services and remittance company, and it believes its new Companion Card can help bridge the gap.
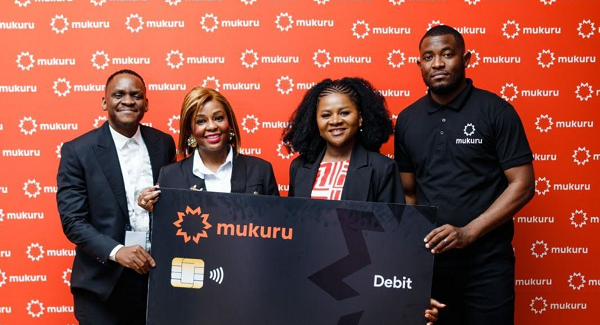
Launched in Botswana in August, the Visa-branded card is linked directly to the Mukuru Wallet. Customers can spend their wallet balance at merchants without first transferring money into a traditional bank account. They can use it for everyday purchases such as groceries, transport, utilities, school fees, and online transactions wherever Visa is accepted.
For consumers who have traditionally received money through remittances or mobile wallets before cashing it out, the card removes a step: the money can remain digital and be spent directly. Thembani Moyo, Country Manager for Mukuru Botswana, told TechCabal that the company is building on behavior customers already understand.
“Our customers already trust the Mukuru Wallet to manage their money. The Companion Card gives them a new, practical way to use it,” he said. “So paying for groceries or topping up airtime is as easy as swiping a card, without ever needing to visit a branch or carry cash.”
In Botswana, mobile connectivity has outpaced formal banking access. Factors such as branch density, affordability, documentation requirements, financial literacy gaps, irregular incomes, and continued reliance on cash all help explain why having a phone has not automatically meant having a bank account. Visa sees a similar gap, but from the infrastructure side.
“This partnership is a clear signal that Botswana’s payments market is maturing beyond a simple cash-versus-remittances dynamic,” said Amon Magunje, Country Manager for Visa Botswana, in comments to TechCabal. “For years, a lot of money movement here has been about cash-out: funds arrive via remittance or mobile wallet, and the consumer’s next step is a trip to a cash point.”
For customers used to cashing out remittances or mobile-wallet balances, the card reduces friction by enabling them to spend digitally. Merchant payments grew 42% to $155 billion in 2025, the fastest-growing mobile-money use case, according to GSMA data.
Visa already works with Botswana’s three mobile network operators and supports more than three million Visa cards through 10 financial institutions in the country. But Magunje believes the next phase of payments growth will come from a different group.
“The Mukuru card extends that same secure rail to a wallet-first, non-bank customer base for the first time,” he said. “It tells us the next phase of growth in Botswana payments won’t just come from banks issuing more cards. It will come from fin-techs and wallet providers plugging into that infrastructure to reach consumers that banks haven’t reached yet.”
Access Bank, meanwhile, views fin-techs and wallet providers as potential partners as much as competitors. Mbatshi Masalila, the bank’s Alliance and Partnerships Manager, said the industry is being forced to rethink what accessibility means.
“Innovations such as digital wallets and companion cards are accelerating the industry’s focus on accessibility and convenience. Mukuru’s wallet and card demonstrate that customers value solutions that are easy to access, require minimal infrastructure, and allow them to transact digitally without necessarily having a traditional bank account,” Masalila noted.
Traditional banks still have capabilities wallets may not, including savings and credit, investments, risk management, and balance-sheet strength. That leaves room for banks, fin-techs, mobile operators, and payment networks to each play a role within the same financial ecosystem. But true scale requires more than surface-level integrations. It demands robust execution that moves beyond announcements and delivers real customer outcomes.