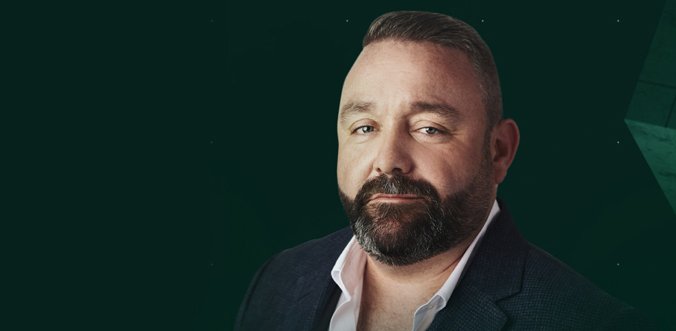
In an industry where many global technology providers still view Africa as an emerging opportunity, Martin Collins sees something far more significant: a strategic growth frontier that is reshaping the future of iGaming. As Chief Commercial Officer of B2Tech, Collins has helped position the company at the forefront of sportsbook and gaming technology innovation across high-growth markets.
With a distinguished career spanning leadership roles at GreenDae, Soft2Bet and Gaming Innovation Group (GiG), he brings a rare blend of commercial expertise, market intelligence and strategic vision. In this exclusive interview with John Bamidele, CEO and Editor-in-Chief of FindMoreAfrica, Collins explains why Africa is no longer an option for B2Tech—it is the strategy, and why the continent’s next chapter in gaming may be its most transformative yet.
What separates the companies that scale globally from the ones that remain regional players?
This is a question I think about differently now than I might have earlier in my career. Being a regional specialist is not a weakness. In fact, in markets like Africa, it is a genuine competitive advantage. The companies that struggle are not the ones who choose a geography and go deep; they are the ones who try to be everywhere without truly being anywhere. What separates successful regional players from those who plateau is the depth of their localisation.
That means payments infrastructure built around how people actually move money, products configured around the sports and content that genuinely matter to that market, and regulatory relationships earned through consistent, compliant operation. I have seen European operators arrive in African markets with world-class technology and fail within eighteen months because they underestimated how differently players behave when mobile money is their primary financial tool and network connectivity is inconsistent.
The companies that scale, whether globally or across a region, are the ones who treat localisation as a core competency rather than a deployment step. The ones that plateau treat it as a translation exercise.
What are the three biggest mistakes iGaming companies make before a sale, acquisition or investment round?
First, they clean up the numbers without cleaning up the story. Investors and acquirers are sophisticated and they will see through inflated retention metrics or one-time revenue spikes. What they actually want is a coherent narrative about sustainable unit economics, and if you cannot tell that story clearly it does not matter how good the spreadsheet looks.
Second, they underestimate the weight of compliance and licensing. I have seen transactions worth tens of millions delayed for months, and in some cases collapsed entirely, because licensing documentation in secondary markets had not been properly maintained. By the time you are in due diligence it is too late to fix.
Third, and this one is chronically underappreciated, they fail to build a compelling synergy case backed by real data. Transparency around your commercial data, your player economics, your market penetration, that is what builds conviction in a buyer. The businesses that attract the best terms are not necessarily the biggest; they are the ones who walk into a room, put their data on the table and let it make the argument for them.
What drives sustainable growth beyond bonuses and promotions from your perspective as a CCO?
Engagement. That is the word I keep coming back to. Bonuses acquire players but they do not retain them. What retains players is a product experience that gets genuinely better the more they use it. When you build personalised journeys, relevant content and interfaces that adapt to individual behaviour rather than serving a generic average, the metrics shift in ways that bonuses simply cannot replicate. In one operator deployment we have worked on, improvements to personalisation and engagement mechanics increased average session duration from under twenty minutes to more than an hour.
That is not a promotional outcome, that is a product outcome, and it has a direct and compounding effect on lifetime value. From a commercial standpoint, sustainable growth also builds through the quality of your operator partnerships. Operators who trust your platform, who grow with you, who are not constantly re-evaluating alternatives, create the kind of durable commercial relationships that are genuinely difficult for competitors to disrupt. Underneath all of it you still need the fundamentals: reliable technology, seamless local payments and a support model that treats partners as partners rather than support tickets.
What’s the difference between a good commercial team and a market-leading commercial organization?
A good commercial team can close deals. A market-leading commercial organisation makes deals inevitable. The difference is in how deeply commercial thinking is embedded across the entire business, not just in the sales function. When product, marketing and commercial strategy are genuinely aligned around operator needs, you stop chasing opportunities and start creating them. The most telling sign of a market-leading organisation is what happens before a formal process begins.
The relationships are already in place. The operator already thinks of you when a problem arises. By the time an RFP is issued, the best commercial organisations have already shaped how the buyer thinks about the problem and what a good solution looks like. That kind of influence does not come from a sales team working in isolation. It comes from an organisation where every function understands what it means to make the customer successful.
Which iGaming businesses are most attractive to acquire today?
The most attractive targets are businesses that have solved a hard problem in a defensible geography. In Africa specifically, that means operators or technology providers who have genuine, deep-rooted market access: real licences, real payment infrastructure, real local relationships, not just a website with a local domain. That kind of presence takes years to build and cannot be reverse-engineered quickly, which is precisely what makes it valuable to an acquirer.
Globally, I would look at companies with strong engagement mechanics and meaningful first-party data assets. As the industry moves away from bonus-led acquisition, businesses that understand their players behaviourally and can demonstrate it in their metrics are going to command serious premiums. And then there is the regulatory access play: businesses that are already compliant and operational in markets that major tier-one operators want to enter but cannot easily navigate alone. That combination of licence, local knowledge and proven operations is genuinely scarce.
In the next five years, will growth be driven more by expansion or consolidation?
Both, but in different geographies, and I think the industry underestimates how divergent those two stories will become. In mature markets, Western Europe and parts of North America, consolidation will accelerate as margins compress and the cost of compliance makes scale a commercial necessity. Smaller operators in regulated Western markets are already finding it difficult to absorb the overhead of responsible gambling obligations, licensing fees and technology investment simultaneously.
But in Africa and Latin America the story is still overwhelmingly expansion. There are significant markets on this continent that are only now beginning to formalise regulatory frameworks and build the digital payment infrastructure that makes scalable iGaming viable. The industry tends to watch those two trajectories separately. The smarter operators will connect them, using the cash flows from consolidated Western positions to fund early-mover expansion in markets where the growth curve is still at its beginning.
What qualities define a top-performing iGaming sales professional?
Understanding the customer’s challenges, genuinely, not superficially. The best people I have worked with do not lead with their product; they lead with curiosity about the operator’s business. They understand the margin pressures the operator is navigating, the player demographics they are trying to serve, the regulatory environment they are operating in. That level of understanding is what earns trust, and trust is what actually closes deals in this industry, not decks and demos.
Beyond that you need resilience, because iGaming sales cycles are long and unpredictable and deals fall over for reasons that have nothing to do with the quality of your offering. You need commercial creativity, the ability to construct a deal structure that genuinely works for both sides rather than just pushing a standard contract. And you need a long-term perspective on relationships. This is a small industry. How you behave when a deal does not close is remembered just as clearly as how you behave when it does.
Which African markets offer the greatest growth potential over the next decade?
Here is a prediction I am fairly confident in: the biggest winners over the next decade will not be the markets attracting the most attention today. The operators flooding into the most talked-about markets are already competing hard on margin and navigating increasingly complex regulatory environments. I would look more carefully at markets where regulation is developing constructively, mobile penetration is climbing fast and the competitive landscape is still genuinely open.
The Francophone West African markets, Ivory Coast, Senegal and Guinea among them, are at an inflection point that reminds me of where East Africa was several years ago. Tanzania, Mozambique and Zambia each have structural characteristics that make them attractive for operators who are prepared to invest in proper localisation rather than a quick market entry.
And Ethiopia, longer term, is simply a very large market that is only beginning to open. The common thread across all of them is the same: get your mobile infrastructure and local payments right and you have a real foundation. Arrive with a European product and a generic go-to-market approach and it will not matter how large the opportunity looks on paper.
As a European iGaming product company entering Africa today, what would be your first three strategies?
Find your local partner before you find your licence. The instinct for European companies is to lead with technology and retrofit local knowledge later, which is completely backwards. Africa will expose that approach quickly and expensively. I have watched well-funded operators spend twelve to eighteen months and significant capital discovering things a genuine local partner could have told them in a week. That knowledge and credibility simply cannot be bought directly; it has to be earned or borrowed from someone who already has it.
Second, treat payments as a product decision, not an integration task. Mobile money is the primary financial rail for the majority of the population across most African markets, and the nuances of how people transact vary considerably even between neighbouring countries. If your payments experience is not genuinely seamless and locally appropriate, your acquisition and retention numbers will tell you immediately.
Third, go deep before you go wide. The temptation to launch across multiple markets simultaneously is understandable but the companies that do it tend to spread themselves thin and fail visibly. Pick two or three markets, build genuine operational depth, learn what actually works and then scale from a position of real strength.
How important is Africa to B2tech’s long-term growth strategy?
It is not part of the strategy, it is the strategy. But I think it is worth explaining why Africa represents such a compelling strategic opportunity for the industry more broadly, not just for us. You have a continent with a young, digitally native population, rapidly expanding mobile connectivity, an extraordinary appetite for sport, and a regulatory environment that is maturing in ways that create genuine, licensable opportunity.
Most of the world’s high-growth iGaming markets from the last decade are now either saturated or heavily taxed. Africa is where the next significant growth cycle will play out, and the operators and technology providers who are building real infrastructure and real relationships here now will have advantages that will be very difficult to displace later.
For B2tech specifically, operating across 22 markets means we have already done the hard work: the licences, the payment integrations, the local partnerships, the operational knowledge. My focus as CCO is to deepen those foundations and ensure our product continues to be shaped by what African operators and players actually need, because that is ultimately what determines whether the opportunity becomes a lasting business.