Money is moving very fast across more borders and through more financial channels than many betting regulators were designed to monitor. Online betting is becoming increasingly digital and cryptocurrency is becoming increasingly mainstream.
Stablecoins are becoming important payment and settlement instruments. The next battle in Africa’s betting industry will not be fought over odds, licenses or market share. It will be fought over the money flowing underneath the bet.
Cryptocurrency is rapidly becoming part of Africa’s financial architecture, while online gambling is becoming increasingly digital, cross-border and payment agnostic. Where these two ecosystems intersect, an uncomfortable regulatory question emerges: can Africa’s financial and gambling authorities actually see the complete transaction? The danger is not cryptocurrency itself.
The danger is opacity, unidentified wallets, fragmented KYC, offshore intermediaries, stablecoins and regulatory gaps that can allow legitimate financial infrastructure to be exploited by criminal networks. For investors, this is no longer merely an AML issue. It is systemic market risk.
In Africa, Cryptocurrency belongs in the betting ecosystem, however the issue is whether regulators, operators, financial institutions and law-enforcement agencies can still follow the money when cryptocurrency enters bet. Chainalysis estimates that Sub-Saharan Africa received more than $205 billion in on-chain cryptocurrency value between July 2024 and June 2025, an increase of roughly 52% year-on-year.
Nigeria alone received more than $92.1 billion, almost three times the amount received by the next largest market, South Africa. Stablecoins are increasingly being used for high-value transactions, connected to trade and merchant payments, illustrating that crypto is becoming part of the region’s broader financial infrastructure.
This is not simply criminal money.
Africans have legitimate reasons to use crypto. Cross-border payments can be slow or expensive. Foreign-exchange access can be difficult. Local currencies can lose value. Stablecoins can provide access to dollar linked digital assets. Businesses can use crypto for settlement while consumers can use it as an alternative financial rail.
Financial Action Task Force (FATF), the global standard setting body for combating money laundering and terrorism recognizes those legitimate benefits. The problem begins when the same infrastructure that makes legitimate transactions faster and more accessible also makes illicit funds easier to move.
The betting connection
A player deposits crypto, places bets, withdraw funds and converts the balance back into fiat or another digital asset.
Who actually knows where the money came from?
This immediately moves the story from cryptocurrency technology to financial transparency. A betting transaction may involve a customer, a betting operator, a payment processor, a crypto wallet, a virtual-asset service provider, a bank and potentially several jurisdictions.
The bet is only the visible part.
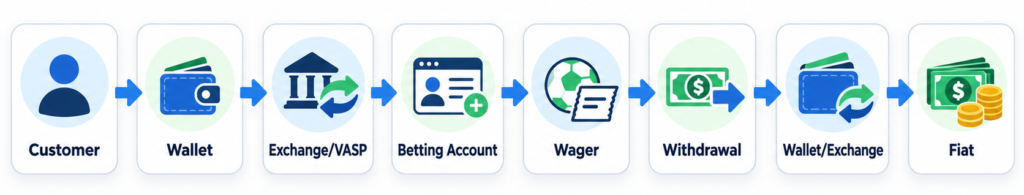
Behind it is a financial chain:
The critical question is simple:
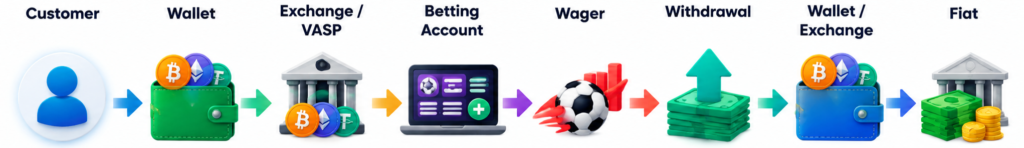
Customer→ Wallet → Exchange/ VASP → Betting Account → Wager → Withdrawal → Wallet/ Exchange →Fiat
The critical question is simple:
Who sees the entire transaction?
The betting operator may know the customer. The exchange may know the wallet owner. The bank may know the account holder. The regulator may know the licensed bookmaker. However, if each institutions sees only one section of the transaction, the complete financial picture can disappear between regulatory borders.
That is the crypto-betting nexus.
FATF’s September 2026 report on gaming and gambling is a major warning. According to FATF, gambling is becoming increasingly digital, cross-border and interconnected, creating new money -laundering, terrorist-financing and proliferation-financing risks. FATF specifically identifies payment channels including e-wallets, mobile money and virtual assets as vulnerable to financial crime.
FATF also found that criminals can exploit gambling platforms to move money without actually gambling, use multiple small transactions to avoid detection, operate through multiple accounts and payments methods and exploit discrepancies between customer and payment information.
That Changes the AML conversation.
Now, the question is no longer simply: Who is the bettor?
It is:
- Who funded the bettor?
- Where did the funds originate?
- Who owns the wallet?
- Has that wallet interacted with suspicious addresses?
- Is the customer actually gambling?
- Where does the money go after withdrawals?
Crypto is not a crime
This distinction matters. Cryptocurrency is not inherently money laundering, just as cash is not inherently criminal. The problem is the potential misuse of the infrastructure.
Stablecoins illustrate the challenge.
FATF reported in March that more than 250 stablecoins were in circulation by mid-2025 with total market capitalization exceeding $300 billion. It also cited Chainalysis data showing that stablecoins accounted for 84% of illicit virtual -asset transaction volume in 2025, representing $154 billion in illicit virtual-asset transaction volume.
That statistic refers to the composition of illicit virtual -asset activity: it does not mean that 84% of all stablecoin transactions are illicit. Stablecoins are attractive to legitimate users because of their relative price stability, liquidity and interoperability.
Those same characteristics can make them attractive to criminals. FATF identifies particular risks involving peer-to-peer transfers through unhosted wallets, where transactions can occur without a regulated VASP or financial institution directly involved in the transfer. Cross-chain transactions can create additional difficulties for controls and tracing.
For gambling operators, this creates an uncomfortable question:
If a customer funds a betting account from a self-controlled wallet, how much does the operator really know about the origin of the money?
KYC alone may not answer that question.
KYC is no longer enough
The traditional compliance model is simple:
Know Your Customer.
However, crypto requires a broader model:
- Know Your Customer.
- Know Your Wallet.
- Know Your Transaction.
A customer’s account may be legitimate while the wallet funding the account is problematic. The wallet may have interacted with high-risk addresses. Funds may have passed through multiple wallets before reaching the betting account. A third party may control the source of the money. The customer may deposit large amounts and withdrawal almost immediately without meaningful gambling activity.
None of these circumstances automatically proves criminality. However, they are precisely the kinds of patterns that risk-based AML systems are supposed to identify and investigate. The industry therefore needs to move beyond static KYC towards continuous transaction monitoring.
Africa’s regulatory fault line
This is where Africa faces a difficult challenge. Gambling regulation, financial regulation and virtual-asset regulation are often administered through different institutions. The bookmaker may sit under a gambling regulator. The bank sits under a financial regulator. The VASP may sit under a security or financial service authority. Suspicious transactions may ultimately be reported to a financial intelligence unit.
The criminal does not care about those institutional boundaries. Money can move from one jurisdiction to another in seconds. FATF’s 2026 review of virtual assets found persistent global gaps in identifying VASPs, licensing and registration, risk-based supervision and enforcement. It also highlighted the risks posed by offshore VASPs operating outside effective supervision.
That is the Real Regulatory Problem.
The issue is not simply whether Africa has AML legislation.
The fundamental is, whether regulators have the technology, intelligence, expertise and cross-birder cooperation to enforce it. A regulation that cannot see the transaction is a rule waiting to be bypassed.
The Security Dimension
It would be irresponsible to claim that cryptocurrency betting is financing terrorism across Africa without evidence. There is, however, clear evidence that criminals and terrorist networks are exploiting assets and digital financial infrastructure. INTERPOL’s operation catalyst conducted across six African countries between July and September 2025, resulted in 83 arrests and the identification of 160 persons of interest.
Authorities screened more than 15,000 people and entities and uncovered approximately $260 million in fiat and virtual currencies potentially linked to terrorism related activities. Eighteen arrests were linked to illicit use of virtual assets. The participation countries were Angola, Cameroon, Kenya, Namibia, Nigeria and South Sudan.
The Kenyan investigation is particularly relevant. INTERPOL reported a suspected money laundering operation involving a virtual-asset service provider with potential terrorism financing links, valued at approximately $430, 000. In another Kenyan case, funds used to recruit the radicalize young people into terrorist groups were traced through cryptocurrency trading platform to individuals in Tanzania.
In Nigeria, 11 suspected terrorists were arrested during the operation. INTERPOL also reported a cryptocurrency-based Ponzi scheme affecting at least 17 countries, including Cameroon, Kenya and Nigeria, with estimated losses of $562 million; investigators found several large financing activities, although the investigation remained ongoing. These cases do not establish that betting platforms were involved.
They established something else: virtual assets are already part of the financial architecture being investigated around serious crime and terrorism financing in Africa.
Africa needs regulatory technology, not regulatory nostalgia
Africa needs better intelligence. Blockchain analytics, wallet screening, transaction monitoring, AI assisted risk detection, enhanced source-of-funds checks and real-time information sharing should become part of the modern AML toolkit. Financial regulators, gambling regulators, VASPs, banks, payment companies, operators and financial units cannot continue to operate as separate islands while the money moves between them. Africa’s regulatory architecture must become as interconnected as the financial system it is supposed to supervise.
The continent is already seeing the consequences of fragmented intelligence. INTERPOL’s recent African operations demonstrate that financial crime, cybercrime, virtual assets, fraud, kidnapping-for-ransom and terrorism financing increasingly intersect. Operation Catalyst itself described those connections as increasingly intertwined. The answer is not to assume that every crypto transaction is suspicious. The answer is to become capable of distinguishing legitimate transactions from suspicious ones.
The real challenge
- The crypto-betting debate is often framed incorrectly.
- It is not crypto versus gambling
- It is not innovation versus regulation
- It is visibility versus opacity
Africa’s crypto economy is growing no doubt and its digital betting economy is also growing. This makes its payment ecosystem more complex while criminal networks are also becoming more technologically sophisticated.
The regulators have a choice.
They can continue regulating the visible layer; the bookmaker, the license and the betting account while the financial infrastructure underneath becomes increasingly complicated. Or better still, they can regulate the entire ecosystem around the transaction. Reason being that, the future of African betting will not be determined only by who is allowed to take a bet. It will increasingly be determined by who can prove where the money behind that bet came from, where it went and who ultimately controlled it.
Cryptocurrency is not the enemy of online betting. Neither is online betting inherently a vehicle for money laundering. The real challenge is whether the regulatory and technological infrastructure surrounding both industries can keep pace with criminals who exploits the space between them.