Uganda gambling sector is entering a more demanding phase, shaped by structural reforms rather than political change. A proposed harmonized 30% tax on gross gaming revenue (GGR), alongside a 15% withholding tax on net player winnings, signals a decisive shift in policy direction. This is further reinforced by the recent suspension of a licensed betting operator and the regulator’s instruction for customers to withdraw their balances clear indicators of a market under tightening control.
At a strategic level, the government’s intent is evident: stronger revenue capture, reduced leakage, and more assertive oversight. However, these measures introduce a parallel reality. Operators are facing higher compliance costs, while players are encountering reduced value. The central issue is no longer about the direction of regulation, but whether the market can sustain this combined pressure without compromising its depth, resilience, and long-term credibility.
The proposed 30% GGR tax reflects a logical effort to simplify the fiscal framework and eliminate inconsistencies across verticals. Harmonization can strengthen enforcement and reduce opportunities for arbitrage. Yet, in practical terms, such a rate represents a significant burden, particularly in an emerging market where margins are already shaped by payment friction, bonus sensitivity, and uneven customer value. Operators are unlikely to absorb this quietly. Adjustments to product mix, promotional strategies, and long-term market participation are likely outcomes.
At the same time, the proposed 15% withholding tax on player winnings introduces a direct impact on user behavior. While efficient from a collection standpoint, withholding is experienced by players as a reduction in returns. In price-sensitive environments, this perception matters. It can quickly influence betting frequency, stake levels, and overall engagement, with some players potentially shifting toward alternative channels perceived as offering better value.
Taken together, these measures create a dual compression effect. Operators face tighter margins, while players receive diminished returns. This simultaneous pressure on both sides of the market is likely to reshape competitive dynamics, placing greater emphasis on efficiency, capital strength, and product differentiation.
The suspension of a licensed operator adds another dimension to this evolving landscape. On one hand, it demonstrates that regulatory oversight is active and willing to intervene to protect consumers. On the other, it introduces questions around market stability. Confidence in a regulated system depends not only on enforcement, but on continuity. A license provides legitimacy, but consistent operation underpins trust.
What is emerging is not a sudden disruption, but a gradual compression of the market. This typically manifests as fewer viable operators, tighter margins, and reduced promotional flexibility, alongside increasing concentration among stronger, well-capitalized firms. While such an environment may be easier to regulate, it can also limit competition, constrain innovation, and raise barriers for new entrants.
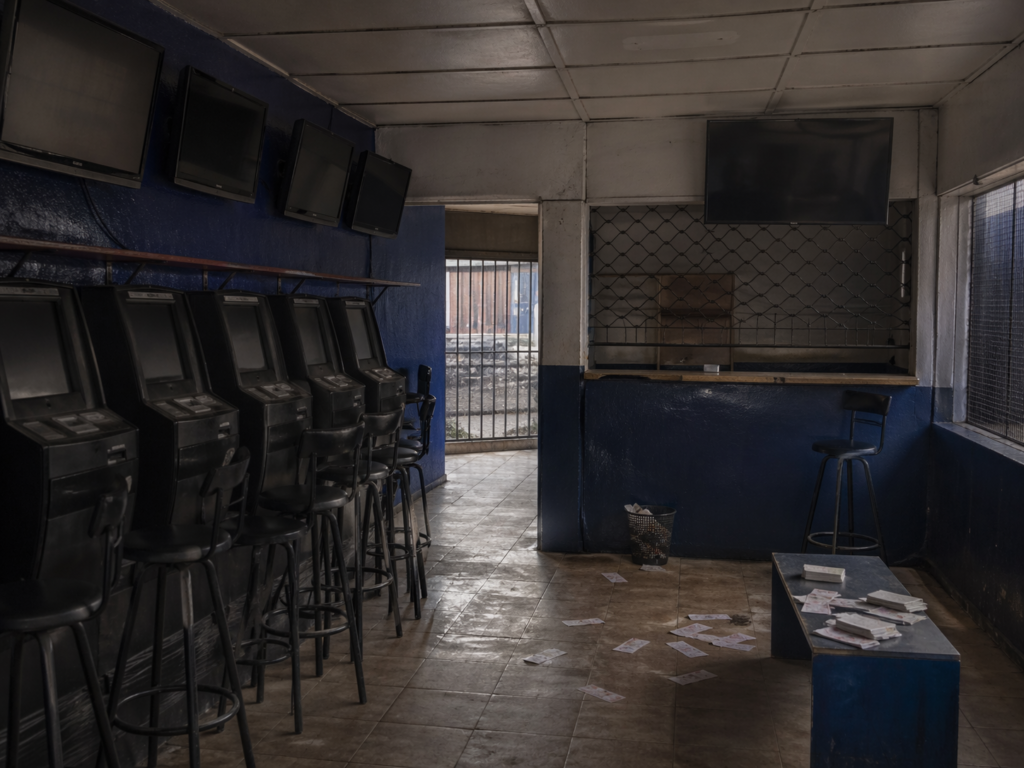
Uganda is, in effect, testing the resilience of its regulated gambling ecosystem. The policy direction is coherent, and the objectives greater control, improved compliance, and enhanced revenue capture are clear. The uncertainty lies in the outcome. If the cumulative burden outpaces the market’s ability to adapt, the result may not be a stronger market, but a smaller and more concentrated one.
In the months ahead, the balance between regulatory control and commercial sustainability will become clearer. What is certain is that Uganda’s gambling sector is no longer in a phase of gradual evolution, it is undergoing a structural shift that will define its future trajectory.